Reconstruction Finance Corporation (1932): Hoover’s Emergency Lending Program
Why Hoover established the RFC in January 1932, who it lent money to, how it changed under Roosevelt and what historians conclude about its effects.
Quick answer
President Herbert Hoover signed the Reconstruction Finance Corporation Act on January 22, 1932, creating a federally backed lender to help stabilize banks, other financial institutions and railroads amid the Great Depression. The RFC began with $500 million in Treasury capital and authority to borrow additional funds. Its powers later expanded to public relief, infrastructure and other purposes. It provided substantial emergency credit, though historians debate how effectively the early program restored confidence and how public disclosure discouraged some borrowing.
Key facts
On this page
- Why the banking crisis called for a new institution
- The Reconstruction Finance Corporation Act of January 1932
- How the initial capital and borrowing authority worked
- Who could receive RFC financing initially?
- The relationship with the Federal Reserve System
- Eugene Meyer and the early RFC leadership
- Loan approvals and the problem of public disclosure
- The Emergency Relief and Construction Act in July 1932
- What changed under Roosevelt and the New Deal?
- Did the RFC help banks survive?
- What became of the corporation?
- Timeline
- FAQs
- Sources
Why the banking crisis called for a new institution
The Great Depression brought financial pressure to banks, businesses and households across the United States. Depositors withdrew money, falling asset prices weakened balance sheets and many lenders became afraid to extend additional credit. Regional banking panics in 1930 and 1931 developed into a wider crisis. An institution that was financially sound under ordinary conditions might nevertheless face danger if it could not obtain cash quickly enough to meet withdrawals. Preventing one failure from triggering others became an urgent federal concern.
Federal Reserve Banks had existing lending tools, but access depended on membership, eligible collateral and institutional practice. Some financial institutions could not easily obtain the assistance they needed, while others feared that seeking emergency support would mark them as weak. Officials therefore looked for a supplementary organization with broader lending authority. The Reconstruction Finance Corporation emerged from this setting, before the most famous bank holiday and New Deal banking laws of 1933.
The Reconstruction Finance Corporation Act of January 1932
On January 22, 1932, President Herbert Hoover signed the legislation establishing the Reconstruction Finance Corporation, commonly abbreviated RFC. The Federal Reserve History project provides an account of its creation and early operation, while the original statute is preserved by the Federal Reserve Bank of St. Louis through the FRASER historical collection. The act authorized the new corporation to make specified emergency loans against security rather than act as a universal source of unconditional gifts.
The decision is often overlooked because the RFC later became associated with Franklin Roosevelt’s New Deal administration. But it was created under Hoover and formed part of his administration’s attempts to stop the banking and credit collapse. Its later expansion was substantial, yet its origin must be dated accurately. The Great Depression overview describes the crisis as a whole; the RFC illustrates a particular federal response to collapsing credit.
How the initial capital and borrowing authority worked
The corporation began with $500 million in capital subscribed by the U.S. Treasury. The original framework also allowed up to $1.5 billion in additional borrowing through its securities, potentially providing roughly $2 billion in total initial financing capacity. The amount was authority and capital support, not proof that every dollar had already been lent out the day the act became law. The RFC could issue obligations and use proceeds to fund qualifying advances within statutory restrictions.
That design was intended to give borrowers confidence that the institution could lend on a meaningful scale while preserving a commercial credit structure. Loans ordinarily required collateral and repayment; the RFC was not created simply to distribute unemployment checks to each household. The distinction between capital, borrowing limits, approvals and money actually disbursed matters when interpreting published figures. Reports from 1932 may describe loan authorizations for banks or railroads that differ from cash payments made by a particular date.
Who could receive RFC financing initially?
The original RFC assisted certain banks and other financial institutions, insurance companies and railroads. These were institutions whose distress could have large consequences for payments, savings, transport and employment. The RFC was meant to supply emergency credit where ordinary financing was hard to obtain, thereby reducing pressure to sell assets at depressed prices or curtail operations suddenly. Officials hoped stabilization at important institutions would help preserve economic activity.
Critics asked why public support flowed first toward banks and large financial organizations when many unemployed families faced immediate hardship. Supporters argued that a collapse of credit could worsen unemployment and deprive small businesses and farms of financing. Both positions were central to the debate. The early RFC did not provide broad household relief directly; it worked primarily through institutional lenders and selected businesses. That indirect approach made its public image vulnerable when economic hardship remained visible.
The relationship with the Federal Reserve System
The RFC was a corporation with federal backing, distinct from the Federal Reserve Banks. It did not replace the Federal Reserve’s role in money and banking, nor was it simply a new branch of one regional reserve bank. It could extend certain loans through its own statutory authority, complementing other emergency measures. Historians describe its initial operations as an attempt to reach credit needs that existing institutions were not adequately meeting.
The Federal Reserve Act of 1913 had created a different institutional framework. By 1932, officials were testing whether that system needed additional support during extraordinary deflation and bank panics. The RFC’s creation therefore illustrates the evolution of federal financial intervention, not a reversal of every earlier central-banking principle. It also highlights how legal eligibility and public confidence could matter as much as the nominal amount of money available for lending.
Eugene Meyer and the early RFC leadership
Eugene Meyer, governor of the Federal Reserve Board, had urged creation of a financing corporation modeled partly on the World War I-era War Finance Corporation. Hoover considered those proposals as the banking crisis worsened. The RFC operated through a board and staff responsible for assessing applications and loan security. Its institutional leadership evolved over the years, especially as its functions changed under later administrations.
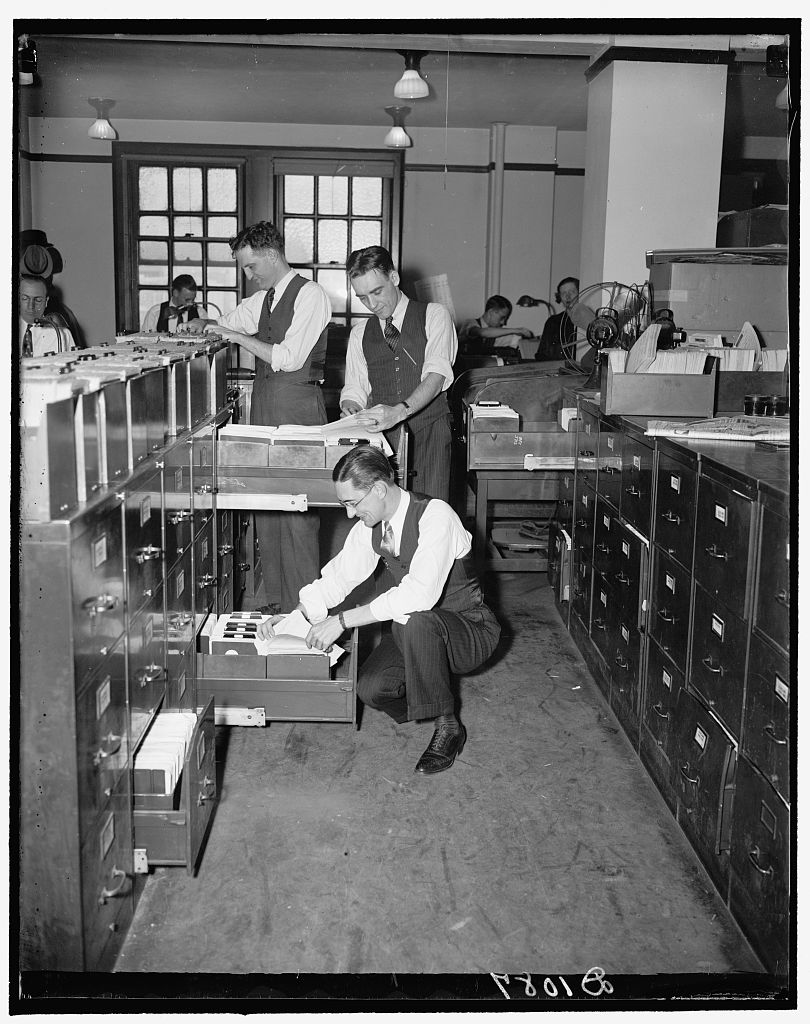
The accompanying photograph shows women clerks checking RFC records in 1937. It documents the detailed paperwork required to administer financial operations several years after the corporation’s creation. Its date is essential: the image should not be labeled a scene from January 1932. Applications, ledgers, repayment records and investigation of collateral formed a practical part of an agency that managed large loans rather than simply announcing rescue packages.
Loan approvals and the problem of public disclosure
By June 1932 Hoover reported that the corporation had authorized hundreds of millions of dollars in loans to thousands of financial institutions and additional assistance to railroads. His public statement described roughly $500 million authorized for about 4,000 banking and related institutions and roughly $170 million for railroads during the corporation’s first fourteen weeks. Those are contemporary administration figures, and they should not be treated as an independent estimate of the program’s final effects.
Congress later required publication of information about borrowers. Some banks feared that public identification as an RFC borrower would alarm depositors and worsen confidence, creating a stigma that discouraged applications. Researchers have debated how significant the disclosure issue was in limiting the program’s effectiveness. It illustrates a difficult dilemma in emergency policy: taxpayers and legislators may reasonably seek transparency, yet publicizing distress can sometimes intensify the financial problem that the program is trying to address.
The Emergency Relief and Construction Act in July 1932
On July 21, 1932, Congress broadened the RFC’s powers through the Emergency Relief and Construction Act. New authority included loans to state and municipal governments for relief and support for specified public construction projects. Borrowing authority also expanded. This marked an important change from the original emphasis on banks, financial companies and railroads. It reflected growing recognition that institutional lending alone could not meet the scale of unemployment and public hardship.
The July expansion did not convert the RFC into the sole administrator of every welfare or infrastructure project. States, local governments and other federal agencies still had major responsibilities. The details of authorizations, loans and eligible projects mattered. But the change helps explain why histories of the RFC describe broader work than appears in the January founding statute. The institution evolved rapidly as the crisis intensified, even before Roosevelt won the 1932 presidential election.
What changed under Roosevelt and the New Deal?
Franklin D. Roosevelt took office in March 1933 amid a severe banking emergency. Rather than abolish the RFC as a Hoover experiment, the new administration used and expanded it. The corporation acquired responsibilities involving bank capital, economic recovery and later industrial finance. Its role became important in restructuring banks and supporting major projects. These changes should be dated separately from the original January 1932 lending powers.
Jesse H. Jones became a central figure in RFC leadership and later described the institution’s work in financial rescue and wartime production. The corporation’s continued existence across administrations demonstrates that policy institutions do not always belong exclusively to the president who founded them. The New Deal overview places these later programs within a broader federal response, while the RFC’s separate history reveals how credit support evolved during the Depression.
Did the RFC help banks survive?
Research using banking data suggests that RFC assistance could improve bank survival and support lending, but the overall assessment depends on timing and program design. Some early loans may have been too cautious, and stigma associated with published borrower lists may have reduced their effectiveness. A bank could also fail for reasons beyond temporary liquidity, including losses so large that a secured loan would not resolve its problems. The RFC therefore cannot be described as a guarantee that every assisted institution remained open.
Federal Reserve History summarizes differing scholarly findings rather than declaring one universal conclusion. The corporation became more flexible in later years, and broader capital support changed what it could accomplish. A measured evaluation distinguishes the original lender-of-last-resort-like support from later investments and policy changes. The RFC was neither a complete cure for the Depression nor irrelevant simply because the crisis continued after its creation.
What became of the corporation?
The RFC survived the Depression, took on substantial work related to World War II production and later faced controversies over lending decisions and governance. Its functions were eventually reduced and reorganized, and the corporation was liquidated in 1957. That long institutional history illustrates the difficulty of defining an emergency agency’s end point once its powers and responsibilities have grown. A body created to rescue banks during the Depression became involved in multiple phases of American economic policy.
Its historical legacy also includes a model for discussions of emergency public lending in later financial crises. That does not mean today’s institutions possess the same powers or should automatically copy its practices. The RFC is useful as a historical comparison because its founding statute, capital structure, early borrowers and later reforms are documented. Its record offers evidence about both the potential and limits of government-backed lending when ordinary financial markets break down.
Timeline
- 1930–1931: Banking panics and credit stress worsen
- January 22, 1932: RFC Act signed
- Spring 1932: Loans to banks and railroads begin
- July 21, 1932: Emergency Relief and Construction Act expands powers
- March 1933: Roosevelt administration takes office
- 1930s–1940s: RFC role grows in finance and wartime production
- 1957: RFC liquidation completed
Frequently asked questions
When was the RFC established?
January 22, 1932, under President Herbert Hoover.
How much capital did it have initially?
$500 million in Treasury capital, with additional statutory borrowing authority.
Did it replace the Federal Reserve?
No. It was a separate federal financing corporation that complemented existing credit institutions.
Who could borrow at first?
Eligible banks, other financial institutions and railroads were important original borrowers.
Did it give direct cash relief to every unemployed person?
No. Its initial program provided secured institutional lending; later laws broadened relief-related powers.
What changed in July 1932?
The Emergency Relief and Construction Act expanded lending to governments for relief and other approved purposes.
Did Roosevelt abolish the RFC?
No. His administration continued and expanded its use.
When did it end?
The RFC was liquidated in 1957.