Sixteenth Amendment (1913): Federal Income Tax, Ratification and History
Why the U.S. Constitution changed in 1913 to allow a modern federal income tax.
The Sixteenth Amendment, ratified on February 3, 1913 and formally declared ratified on February 25, permits Congress to tax incomes from whatever source derived without dividing the tax among states by population. Congress had proposed it in 1909, after an 1895 Supreme Court ruling restricted certain federal income taxes. The amendment enabled the modern federal income tax, but Congress enacted the actual tax law separately in October 1913.
The amendment’s exact powers, earlier income-tax history, key dates and the tax law Congress enacted later in 1913.
On this page — 22 topics
What is the Sixteenth Amendment?
The Sixteenth Amendment to the United States Constitution authorizes Congress to impose taxes on incomes from whatever source derived without apportioning the tax among states according to population. Congress proposed the amendment in 1909, and enough states had ratified it by February 3, 1913. It responded to constitutional disputes over income taxes that arose after a Supreme Court ruling in 1895. The amendment did not itself set tax rates, create the present-day Internal Revenue Service or instruct every American to submit a specific form. It removed a constitutional obstacle so that Congress could enact modern federal income-tax legislation. The actual federal income tax adopted later in 1913 was contained in a separate revenue statute.
What does the amendment actually say?
The amendment states that Congress has power to lay and collect taxes on incomes, from whatever source derived, without apportionment among the several states and without regard to any census or enumeration. Its language is short but consequential because the original Constitution treated direct taxes and certain other forms of taxation differently. The phrase about income sources addresses the power of Congress to tax different forms of income without a state-by-state population formula. It is not a complete revenue code, and it does not specify exemptions, deductions, tax brackets or filing deadlines. Those matters depend on statutes and regulations enacted under the constitutional authority. The National Archives preserves the original wording.
When was the Sixteenth Amendment ratified?
The required number of states had ratified the amendment on February 3, 1913, according to the National Archives. Secretary of State Philander C. Knox formally proclaimed the result on February 25, 1913. These two dates represent different steps: completion of ratification and official notification or certification. The amendment had been submitted by Congress several years earlier, in July 1909. Histories that assign it to President Woodrow Wilson’s signing of a tax bill confuse constitutional ratification with later legislation. Wilson took office on March 4, 1913, after the amendment had already gained the required state approvals. Its success depended on congressional action and decisions by state legislatures, not a single presidential signature.
When did Congress propose the amendment?
Congress approved the proposal on July 2, 1909, during the presidency of William Howard Taft. It was then sent to the states for approval under Article V of the Constitution. In 1913 there were forty-eight states, requiring at least thirty-six to approve a constitutional change. The long ratification process reflected different state political priorities and debates about federal fiscal power. The proposal preceded Wilson’s administration and the Underwood tariff reforms that followed it. This timing explains why some historical references associate the amendment with Taft and others with the Progressive Era legislation of 1913. Both contexts matter, provided the dates and separate government actions are identified precisely.
Why were income taxes constitutionally controversial?
The U.S. Constitution gives Congress broad taxing powers but imposes rules concerning direct taxes and the apportionment of certain revenues among states. A tax apportioned by population would need to allocate the amount owed by each state using its population, an awkward method when taxable income differs from one state to another. The Supreme Court examined whether particular income taxes fell under these constitutional restrictions. The Sixteenth Amendment clarified Congress’s authority to tax incomes without using that population formula. It did not remove every constitutional limitation on taxation or automatically validate any tax Congress might imagine. Its principal importance was resolving a problem that had blocked a politically significant approach to raising national revenue.
Did the United States have an income tax before 1913?
Yes. The federal government imposed income taxes during the Civil War, beginning in 1861 and developing further under later wartime revenue laws. Those taxes helped finance military operations and ended in the postwar period. Congress tried again with a federal income tax in 1894, but litigation over that measure produced a constitutional conflict. The popular claim that the government had never taxed income before the Sixteenth Amendment is therefore incorrect. The amendment’s significance was not inventing the idea of an income tax. It provided explicit constitutional authorization for a system that Congress could establish more durably, without having to meet the earlier apportionment requirement.
What happened in the Pollock decision of 1895?
In Pollock v. Farmers’ Loan & Trust Co. the Supreme Court struck down key parts of the federal income tax adopted in 1894, holding that certain taxes on income from property required apportionment under the Constitution. The ruling severely limited the practical viability of that national tax system. It did not establish that all possible taxes on incomes had always been unconstitutional. The case became an important political issue because reformers viewed the restriction as favoring wealthy property owners and limiting the national government’s ability to shift revenue away from tariffs. The Sixteenth Amendment directly responded to the constitutional problem, changing the legal basis for future federal income taxes.
Why did reformers favor an income tax?
Supporters argued that a national income tax would allow government to draw a greater share of revenue from people with substantial earnings or investment returns rather than depending so heavily on tariffs and excise taxes. Protective tariffs could raise the price of imported products and affect consumers differently from a tax based on income. Reformers disagreed about tax rates and the proper size of government, but many advocated a broader revenue base and a more graduated tax system. Critics worried about central power, administrative burdens and effects on investment. The debate reflected wider Progressive Era concerns about wealth distribution and national public responsibilities. The amendment did not resolve those disagreements, but it made federal income taxation a practical constitutional option.
What did President William Howard Taft propose?
In 1909 Taft supported a constitutional amendment that could overcome the problem created by the 1895 Pollock decision. His position also reflected negotiations over tariff legislation and competing approaches to taxing corporations and individuals. The amendment went through Congress and required action by state legislatures rather than the president signing a constitutional change into existence. Taft later lost reelection in the 1912 presidential contest, so Wilson was president when Congress enacted a major revenue law in October 1913. Distinguishing the political roles of Taft and Wilson helps prevent a misleading narrative in which the entire process is attributed to one administration.
Why was state ratification necessary?
Article V of the U.S. Constitution requires proposed amendments to receive approval under a specified federal and state process. A two-thirds vote in each house of Congress is necessary to propose an amendment through that route, and ratification by three quarters of the states makes it part of the Constitution. Presidents do not approve or veto constitutional amendments as they do ordinary bills. The Sixteenth Amendment passed through state legislatures over several years. Its adoption illustrates that nationwide constitutional changes depend on more than the federal election of a president. The process also helps explain why the amendment’s ratification date differs from the date Congress subsequently imposed an income tax through ordinary legislation.
How did the 1913 Revenue Act use the new authority?
The Revenue Act of 1913, often called the Underwood–Simmons Tariff Act, reduced important import duties and established a federal income tax under the constitutional authority recognized by the Sixteenth Amendment. President Wilson signed the revenue legislation on October 3, 1913. It introduced a graduated structure in which rates rose for higher taxable incomes. Not everyone was required to pay, because exemptions and income thresholds applied. The new tax was part of a wider shift away from reliance on customs duties. The amendment allowed Congress to act, but the October law specified the actual tax obligations and mechanisms. This difference is fundamental: a constitutional power is not the same thing as the statute exercising it.
What were the original income-tax rates?
The 1913 income tax imposed a normal tax of one percent on taxable income above statutory exemptions, with additional graduated surtaxes on higher incomes. The highest effective marginal rate under the original system is commonly summarized as seven percent. These rates should be understood in their historical context and not applied to the modern tax system. Exemption thresholds meant that a substantial portion of the population did not owe income tax under the initial structure. Rates and brackets changed rapidly in later years, particularly as the United States financed its involvement in World War I. An accurate comparison specifies both tax year and income category, rather than treating one 1913 figure as the rate paid by every American.
When did the first Form 1040 appear?
The early federal income tax required taxpayers meeting statutory conditions to submit returns describing their income and calculating liability. The first Form 1040 associated with the modern system was produced for the 1913 tax year, with filing activity following under the new law. Historical examples of the first form are preserved in Library of Congress and National Archives materials. The design and information requirements were much simpler than present-day federal tax filings, but they still involved categories of income and exemptions. The Sixteenth Amendment did not itself create a form called 1040. That was an administrative instrument developed by the federal revenue service to implement the tax legislation enacted after ratification.
Was there an IRS in 1913?
The federal government had a Bureau of Internal Revenue during the early twentieth century, descended from revenue institutions established during the Civil War. The name Internal Revenue Service became officially associated with the modern agency later, in the twentieth century. It is acceptable in casual discussion to refer to the IRS as the successor institution, but a historical description of administration in 1913 should identify the Bureau of Internal Revenue where precision matters. The bureau administered tax collection under congressional statutes and Treasury regulations. Its role was distinct from that of the Federal Reserve System, created later that year to address banking, currency and credit.
Did the Sixteenth Amendment require every worker to pay taxes?
No. The amendment authorizes a kind of federal taxation; it does not require Congress to tax every dollar earned by every person or eliminate statutory exemptions. The actual tax laws specify which income is taxable, when returns are required and how liabilities are calculated. In 1913 exemptions meant most Americans did not face the same obligations as high-income households. The precise modern rules have evolved through many amendments, court decisions and administrative changes. Claims that the Sixteenth Amendment directly instructs all people to file an annual return confuse constitutional authority with tax statutes. As a historical matter, Congress’s legal power and the obligations it chooses to impose through legislation are separate questions.
What did the Supreme Court decide in Brushaber?
The Supreme Court’s 1916 decision in Brushaber v. Union Pacific Railroad Co. addressed constitutional challenges to the federal income tax enacted after the Sixteenth Amendment. The Court upheld the legality of the tax in the face of arguments about the amendment, apportionment and related constitutional principles. The decision became an important part of the law’s early judicial interpretation. It did not create a new constitutional amendment or establish the tax for the first time. The underlying legislation had been enacted in 1913. The case illustrates that even after the amendment was ratified, opponents continued challenging the details of federal taxation, while courts developed the legal principles applying the new constitutional language.
How did World War I change income taxation?
American entry into World War I in 1917 increased federal revenue needs dramatically. Congress raised income-tax rates, expanded the number of taxpayers and adopted other wartime measures. The scale of taxation changed considerably from the limited structure created in 1913. This evolution was possible within the constitutional authority of the Sixteenth Amendment but occurred through subsequent legislation. Historical accounts that list wartime rates as though they were imposed by the amendment itself are mistaken. The war revealed the importance of a flexible national revenue system for major public commitments. It also provoked debate about how heavy taxation should be distributed among earnings, capital and consumption.
How is the amendment related to the Progressive Era?
The income-tax amendment belongs to a broader period of institutional reform that also produced changes in banking, corporate oversight and electoral representation. The Seventeenth Amendment, ratified in April 1913, changed how U.S. senators were elected. The Federal Reserve Act created a new banking structure in December. The Clayton Antitrust Act and Federal Trade Commission Act followed in 1914. Each reform addressed a different public problem, but together they illustrate political demands for a national government capable of responding to industrialization and concentrated economic power. The Sixteenth Amendment’s contribution was to clarify federal revenue authority, not to govern bank operations or elections.
What is the amendment’s lasting significance?
The Sixteenth Amendment became a central constitutional foundation of the modern American income-tax system. It allowed Congress to design federal taxes on income without dividing the tax burden among states by population. Over time national revenue and the government’s responsibilities expanded well beyond what legislators in 1909 or 1913 might have anticipated. The amendment did not freeze tax rates or create one permanent revenue statute; Congress has repeatedly revised tax laws within constitutional limits. Studying its history explains how a Supreme Court decision in 1895, debates over tariff revenue, state ratification and legislation in 1913 came together to establish a durable framework for federal taxation.
Sixteenth Amendment timeline
| Date | Event |
|---|---|
| 1861–1872 | Federal government uses Civil War-era income taxes. |
| 1894 | Congress enacts another national income tax. |
| 1895 | Pollock decision blocks key parts of 1894 tax. |
| July 2, 1909 | Congress approves proposed Sixteenth Amendment. |
| February 3, 1913 | Three-fourths of states ratify. |
| February 25, 1913 | Secretary of State Knox proclaims amendment ratified. |
| October 3, 1913 | Wilson signs Revenue Act establishing an income tax. |
| 1916 | Supreme Court decides Brushaber. |
| 1917–1918 | Wartime legislation sharply expands income taxation. |
Historical sources
- National Archives — Sixteenth Amendment
- National Archives — Constitution Questions and Answers
- National Archives — First Form 1040 and 1913 Law
- Library of Congress — Sixteenth Amendment Newspaper Guide
- Library of Congress — First Form 1040 History
- Library of Congress — April 15 Tax History
- Supreme Court — Brushaber 240 U.S. 1 (1916)
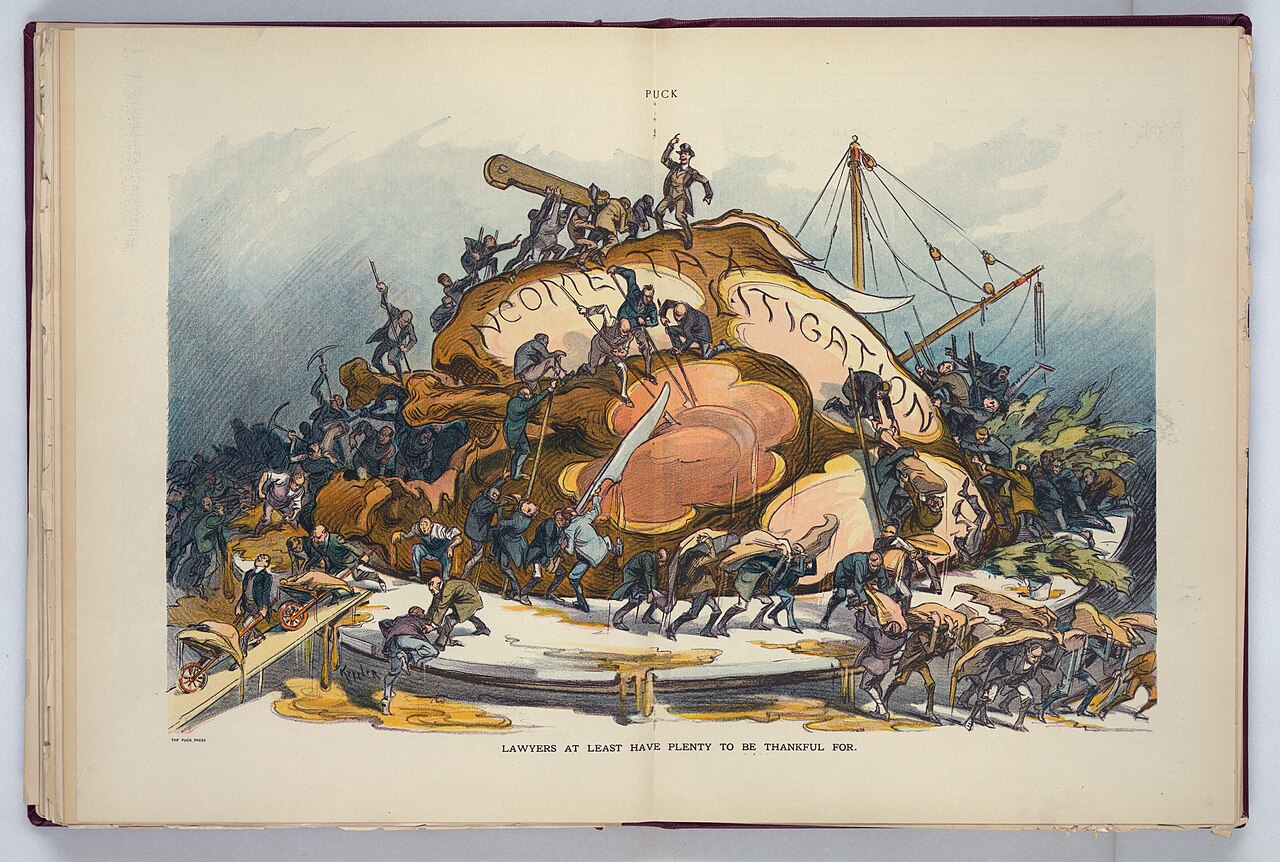
- 1913 Tax Cartoon — Library of Congress